Thematic viewpoint
Sahil Mahtani – Strategist
The start of a fresh year offers good reason to review the structural themes that we believe are going to dominate macroeconomic and market developments over the next decade.
Ninety One Investment Institute’s Road to 2030 project is designed to highlight undiscounted change. We believe that understanding the key long-term structural thematic drivers is the basis of good strategic investment thinking and can generate a clear understanding of the key drivers that can provide a valuable analytical advantage. Each decade, getting that one big decision right was the most important driver from investment returns, be it Japan in the 1980s, globalisation in the 1990, or, more recently, the rise of scalable global businesses, led by the technology sector.
Looking to 2030, we have identified five overarching themes that give us a structure for our thinking:
The Rise of China: China is undergoing three distinct transformations. First is the shift from fixed asset investment to consumption, second is the shift up the value chain as China seeks technological independence in key areas, and third is China’s outward economic expansion. The US response to these transformations is a crucial overlay, focusing on security competition; data regulation is going to be a major arena of competition over the next decade.
Climate Change: The key distinction here is between physical risks – changes to the planet – and transition risks as businesses and households alter their behaviours. Climate change modelling is complex, but it is generally agreed that the main physical risks over the next decade are extreme weather events rather than permanent changes in the physical environment. Transition risks are the key business risk—and opportunity— until 2030. The world remains, for instance, US$2 trillion short of investment in decarbonisation—something our industry has a major role to play in.
Technological Disruption: Our key insight is that technology is not a sector, but an enabler to new and existing businesses, and we have therefore divided this bucket into five functional areas. First is better healthcare, by which we mean more preventive therapies and new, potentially cheaper, treatments. Second is the growing abundance of goods and services, third is the shift to a more flexible workplace, fourth are innovations in personal mobility and finally, we believe states are going to take a much more activist stance on the economy.
Debt: The last four decades have seen an explosion in public and private debt growth around the world, facilitated by declining real and nominal interest rates and latterly by quantitative easing. Unexpected events like COVID-19 have merely accelerated the trend towards the debt build up. We think a combination of measures are likely to be pursued to stabilise these high debt levels: financial repression; competitive devaluations to boost exports; more austerity and taxation; reform and growth; macroprudential policy; helicopter money; private debt forgiveness.
Demographics: We have split this vast and hugely important topic into the effect on government budgets, the impact on GDP and some idiosyncratic effects. As people age, pension liabilities will increase, as will healthcare costs, squeezing non-welfare spending. Older people are likely to dominate the political agenda, newer products are likely to emerge to cater for old age care, and there is the potential for a “depopulation dividend,” as quality of life improves in a more environmentally friendly world.
Following extensive analysis of these five themes, we have then considered a number of scenarios on each one to convey the plausible futures that may result. They ask investors to think through the investment judgment they would make if certain conditions are fulfilled and therefore before the decision actually has to be taken.
COVID-19’s impact on these themes
COVID-19 has accelerated key drivers behind each of these themes. China’s ascent up the value chain has clearly been accelerated by the pandemic, with the Chinese government now more committed to spending heavily to secure its own semiconductor supply base. Similarly, the US response to China has been sharpened as a result of COVID-19, with the US now more committed to abandoning its previous permissive strategic stance on China.
Key technological disruption trends have also been accelerated, including: a transformation of the workplace (through the rise of home-working and a shift towards the globalisation of services), a shift towards better healthcare (the unprecedented discovery of multiple effective vaccine candidates in the span of months), an increasing abundance of goods and services (the pandemic-driven rise of e-commerce and video games), and an increasing focus on innovations in personal mobility (the rapid increase in market capitalisations of electric-vehicle companies) .
The pandemic has also driven home the need for longer-term thinking and our interconnectedness, facilitating a new movement towards climate change resilience. Governments are increasingly promising to raise carbon taxes, fund innovation, and generally commit to replacing less-efficient energy devices with more efficient ones. In September and October, China, South Korea and Japan all committed to net-zero emissions by 2060. In Europe, one in every 10 cars sold in 2020 was an electric or plug-in hybrid, triple the level last year. The US will commit to the Paris Agreement under a Biden administration. This theme will experience ongoing cyclical and secular tailwinds driven by government policy and regulatory developments.
Meanwhile, for the debt theme, fiscal deficits in 2020 are likely to be 11.1% of GDP in emerging markets and 15.6% in developed markets. Debts are now spiking and will only stabilise as the recovery takes hold. Governments will use a number of tools to keep public and private leverage sustainability in check, including financial repression, currency wars, austerity/taxation, macroprudential policy and selective debt forgiveness. Given the rise in income and wealth inequality during the pandemic, as well as the imperative to restore the pre-pandemic economic order, it will be very difficult for states to pursue austerity and taxation as some did in the 2010s. Therefore, we are more likely to see a consensus building towards the use of unorthodox solutions. The 2010s may well come to be seen as the last gasp of fiscal responsibility, as traditionally understood.
On demographics, the long-term effects of COVID-19 may turn out to be more protected health budgets and healthcare spending. Combined with efforts to reduce obesity and increase vitamin-D intake, this could lead to longer lifespans in the years ahead. Meanwhile, the working-from-home trend, enabled by technological disruption, may also increase labour-market participation as flexible working widens opportunities to more people.
The range of outcomes remains wider than usual, but the contours of the next regime are already coming into view. COVID-19 has increased the possibility of a regime shift with the possibility of faster productivity growth, a material shift in economic activity towards Asia Pacific, a policy shift driven by governments actively targeting growth and not just inflation, and of generally a greater need to ensure shared prosperity amidst widespread inequality and digitalisation. As such thematic analysis continues to be highly relevant for investors.
China arguably still has a significant growth runway. Its urbanisation rate is similar to that of Japan in the 1970s, not the early 1990s. Meanwhile, China’s capital stock per worker is still substantially lower than Japan’s or Korea’s
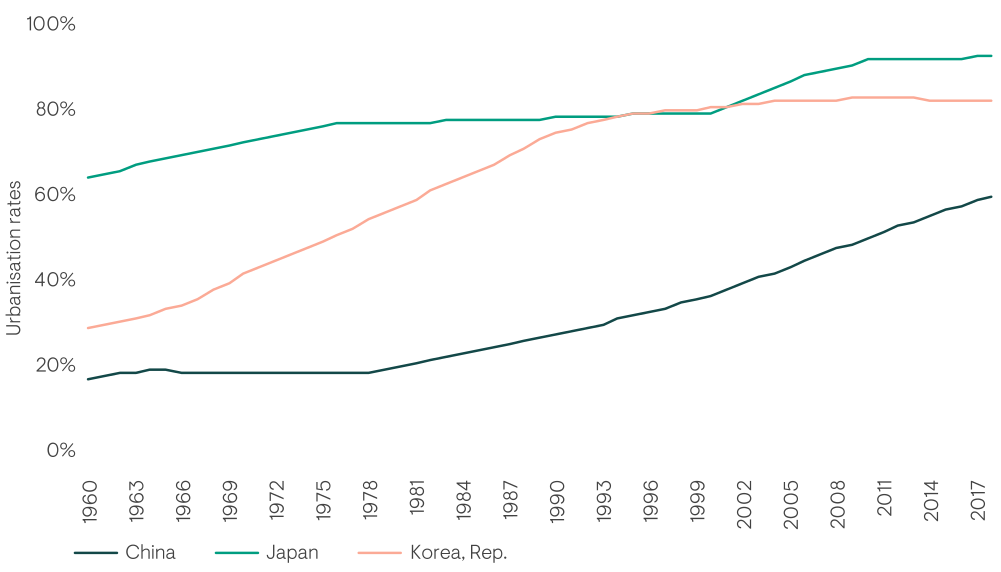
Source: The World Bank; Penn World Tables.
Download PDF