0:00
0:00
Key takeaways
- Earnings momentum is returning as monetary and fiscal stimulus feed through to corporate profits.
- Selectivity matters — opportunities lie in Europe, specific emerging markets and parts of the US tech sector.
- Conviction in commodities — we remain positive on the long-term outlook for gold and PGMs.
- Position early, stay invested — careful and timely positioning can deliver meaningful gains, as seen with Rheinmetall.
How much further can equities run? After a year of powerful gains, led by a narrow band of global stocks and a handful of local standouts, that question hangs over every asset allocation discussion. It’s a good problem to have, but a tricky one to solve. Because when both valuations and expectations are elevated, asset allocation and selection matter more than ever.
This environment has posed both opportunities and challenges for our Global Balanced Strategy. For the past two to three years, re-rating rather than earnings growth dominated returns, an environment less suited to our style. That trend now appears to be reversing. Valuations are normalising and earnings upgrades are once again driving share price performance, both in South Africa and abroad.
Europe leads the shift
This shift matters. When valuations are already elevated, further gains depend on companies delivering real earnings growth rather than benefitting from higher multiples. Markets are now rewarding those upward revisions, with improving data across areas within Europe, select emerging markets and parts of the US. For investors like us, whose process focuses on identifying earnings momentum early, this marks a turn in the cycle, one that plays to our strengths.
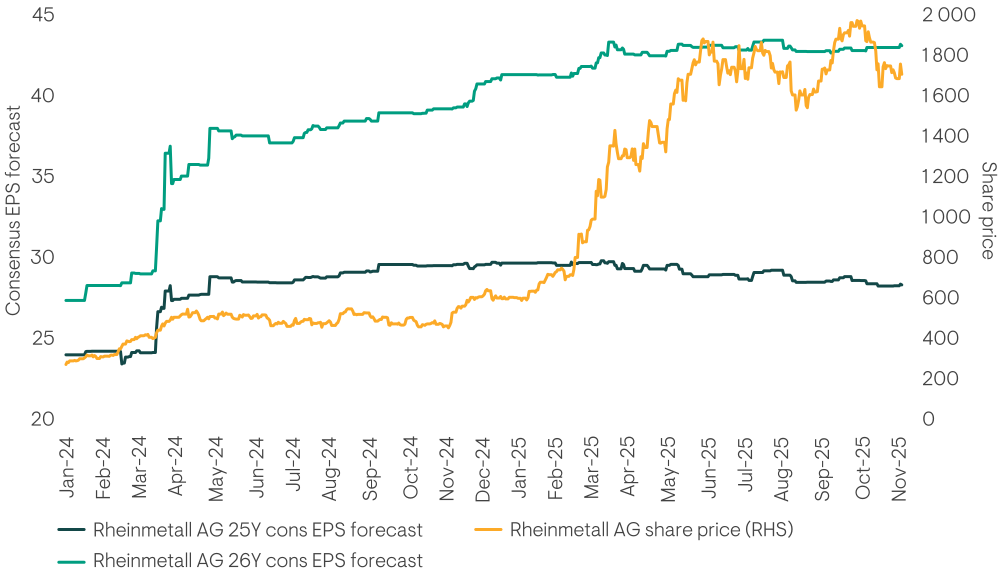
Rheinmetall1, the German arms and automotive group, is a telling example. We first took a position in 2024, backing evidence of strengthening earnings momentum. Since then, the stock has seen exceptional returns, soaring by more than 220% year-to-date, fuelled by surging defence budgets and a swelling order book. We added to the position as Europe’s fiscal push gathered pace, turning an early idea into a decisive contributor to recent returns.
Figure 1: Rheinmetall consensus earnings vs. share price
Source: Bloomberg, November 2025.
Rheinmetall is just one example of how this approach is playing out in Europe. We remain overweight in the region and selectively positioned in the technology sector, two areas where the investment case continues to build. Alongside Rheinmetall, we’ve identified other opportunities in Europe, such as Prysmian SpA and Siemens, where improving earnings visibility and policy support should drive performance over time.2 Across the region, monetary and fiscal stimulus are beginning to show up in corporate earnings revisions. Financials and cyclical industrials, long held back by weak growth expectations, are now seeing upgrades as confidence returns. The portfolio’s exposure to these sectors reflects our belief that Europe’s policy environment and fiscal push can translate into a sustained recovery rather than a short-lived bounce. We expect improving industrial activity to lead to stronger consumer confidence in the months ahead.
US opportunities broaden
We are also constructive on the US economy. The slowdown there looks more like a soft landing than a contraction, creating conditions for rate cuts that could reignite growth and improve sentiment, an encouraging backdrop for equities.
Our focus remains on well-positioned growth and technology names, companies with genuine earnings momentum and structural demand rather than those lifted purely by sentiment. We expect leadership in US equities to broaden beyond the ‘Magnificent Seven’, as technology-related investment and infrastructure spending lift a broader range of companies benefitting from this capex cycle.
While these trends are encouraging, we’re mindful that markets have run hard this year. Fundamentals remain supportive, while sentiment and positioning are now more neutral. However, valuations are high. Given this backdrop, we remain constructive on equities but have taken some profits on select offshore holdings and are holding some cash, ready to redeploy when the opportunity presents itself.
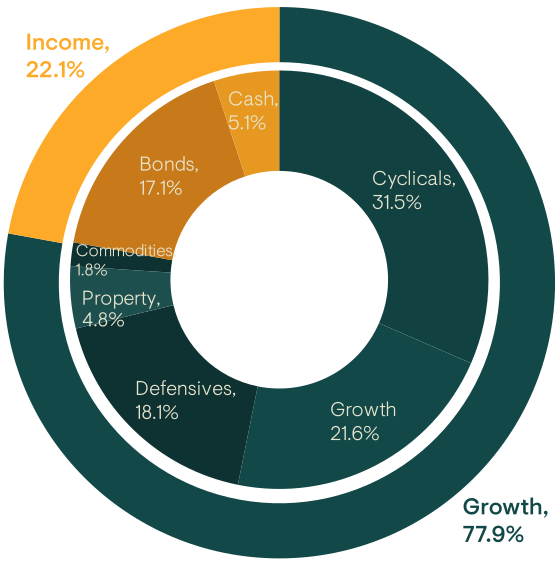
Figure 2: Asset allocation
Source: Ninety One, 30 September 2025.
| As a % of total fund | 31-Dec-24 | 30-Sep-25 |
|---|---|---|
| Cyclicals | 36.5% | 31.5% |
| Growth | 24.3% | 21.6% |
| Defensives | 12.2% | 18.1% |
| Equity assets | 73.0% | 71.2% |
| Property | 4.6% | 4.8% |
| Commodities | 1.0% | 1.8% |
| Total growth assets | 78.7% | 77.9% |
| Bonds | 16.5% | 17.1% |
| Cash | 4.9% | 5.1% |
| Total income assets | 21.3% | 22.1% |
| Total Offshore | 38.9% | 34.6% |
| Total SA | 61.1% | 65.4% |
| ZAR-exposure | 61.2% | 65.4% |
Commodities confirm the process
At home, gold and Platinum Group Metal (PGM) shares1 have been the standouts. Our earnings-driven approach identified early signs of recovery in these sectors, and our overweight positions have been key contributors to portfolio returns. We remain confident in the long-term outlook for both metals. Gold’s more sustained rally continues to be underpinned by structural drivers, including high global debt levels, ongoing fiscal spending, persistently low real interest rates and central bank diversification away from the dollar. Meanwhile, PGMs offer cyclical and fiscal tailwinds, as improved profitability supports both the economy and tax revenues.
That said, sentiment around gold has become stretched in the short term. Prices and shares have run hard, and valuations now look full. We’ve therefore trimmed exposure, locking in gains while keeping conviction in the underlying fundamentals.
Beyond resources, the broader South African equity landscape is showing signs of improvement. If the South African Reserve Bank succeeds in anchoring inflation expectations closer to 3%, it could pave the way for lower nominal interest rates and a rerating of interest rate-sensitive sectors such as banks. Despite falling bond yields, banks have yet to rerate meaningfully, a potential opportunity as the market’s focus shifts from precious metals to domestically geared names.
Patience is rewarded
The Strategy remains balanced, patient and selective. While we continue to find opportunities in both local and global equities, South African bonds still offer attractive real yields and serve as a stabiliser within the portfolio. By staying disciplined, anchored in fundamentals, valuations and sentiment, we aim to capture earnings-led opportunities across markets while maintaining the flexibility to respond as conditions evolve.
1 No representation is being made that any investment will or is likely to achieve profits or losses similar to those achieved in the past, or that significant losses will be avoided. This is not a buy, sell or hold recommendation for any particular security. For further information on specific portfolio names, please see the Important information section.
2 Forecasts, opinions and commentary reflect current views and are not guaranteed to occur.
